
RDTI24 An analysis of the Research & Development Tax Incentive Transparency Report data from FY2023-24
Published
The program
A word from Kashcade, the key findings, and how the program grew in FY24.
A Word From Kashcade
This is the third year we have published what the Transparency Report data truly shows. But this year, it matters more than usual.
Treasury's exposure draft of the 2026-27 Budget R&D changes closes for comment on 28 September. This report is the most recent view of the program they will reshape.
The RDTI program is showing signs of consolidation. Claimants grew just 3% and expenditure 1% in FY24, and 40% of returning claimants reduced their claim.
Beneath that, the data shows that innovation runs on a longer clock than the policy assumes. The median claimant is now 7.3 years old. The biggest spend growth came from companies aged 9 to 12. Companies past year 10 carry 54% of all R&D expenditure. For those under the turnover threshold, the refund pays for engineers and funds the next stage of R&D.
Australia needs more companies doing a variety of R&D, for longer. Participation is less than half of Canada's and slipped this year. The UK shows the risk of policy change. After reforms tightened its scheme, participation roughly halved in two years, and first-time claimants fell 45% in 2023-24 alone. Refundability should not be set by company age.
If these changes affect you or your community, make a submission while the draft is open.
Thank you to those in the community who contributed to this report. I hope it is useful.
Alex Simmons, Co-Founder & CEO, Kashcade
At a Glance: Key Findings from the 2023-24 Transparency Report data
From the ATO RDTI FY24 Report Findings
13,490 companies claimed a record $16.7 billion in FY24. Growth settled to low single digits after FY23's spike, a program consolidating at a permanently higher base.
Large public and multinational businesses remain the primary contributors, claiming $9.0 billion (54% of the total), yet make up only 18% of the claimants.
Small businesses drove the year's growth, lifting their R&D expenditure 28% to $3.1 billion and their claimant numbers 15% to 6,920, now 51% of all claimants.
Companies more than 10 years old make up 37% of claimants and 54% of all R&D expenditure. 7% of claimants sit below the proposed $50,000 floor.
The RDTI program grew marginally in FY24
| FY23 | FY24 | |
|---|---|---|
| RDTI claimants | 13,121 | 13,490▴3% ▴369 |
| RDTI expenditure | $16.5B | $16.7B▴1%* ▴$0.2B |
*The ATO's reported 3% expenditure growth compares FY24 data against FY23 as first published (incomplete); like for like, true growth was 1%.
Note: FY23 figures are restated from the 12,956 claimants and $16.2B published in Kashcade’s FY23 report, as companies lodging after the ATO's cut-off have since entered the dataset.
The reforms
What the proposed changes expand and narrow, and who the 10-year limit and $50k floor reach.
The proposed reforms trade higher rates for tighter eligibility
What expands:
- Higher offsets for eligible core R&D activities
- Refundable offset turnover threshold rises from $20 million to $50 million
- Maximum expenditure threshold rises from $150 million to $200 million
- Non-refundable offset intensity threshold falls from 2% to 1.5%
What narrows:
- Supporting R&D activities removed from eligibility
- Minimum expenditure threshold rises from $20,000 to $50,000
- Refundable offset limited to firms up to 10 years old, or up to 15 years for eligible firms doing therapeutic-goods R&D
The RDTAA welcomes the expansions, but has serious concerns. The changes will make eligibility far more complex for claimants and regulators, and the 10-year rule and higher threshold will shut out many startups and SMEs.
We strongly urge enhanced consultation before the legislation progresses.
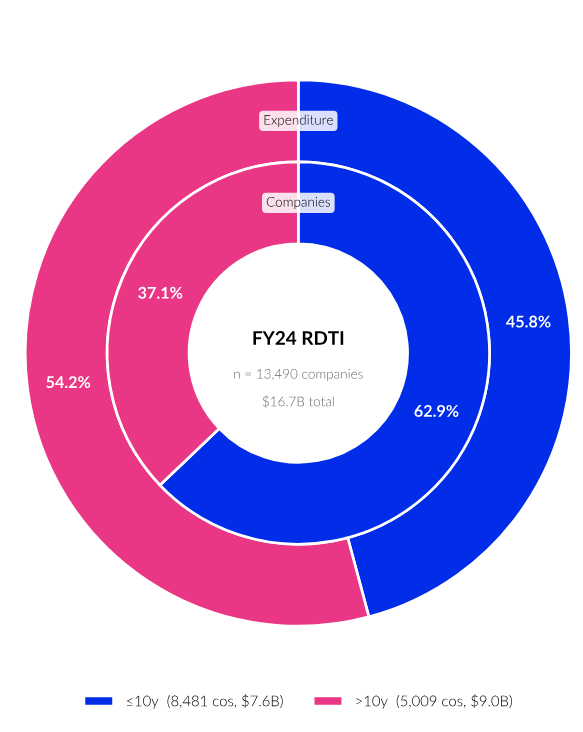
Most R&D spend comes from companies past year 10
The proposed 10-year refund limit reaches the program's core
View the data
| Company age | Claimants | Share | R&D expenditure | Share |
|---|---|---|---|---|
| 10 years or under | 8,481 | 62.9% | $7.6B | 45.8% |
| Over 10 years | 5,009 | 37.1% | $9.0B | 54.2% |
- Companies more than 10 years old make up 37% of claimants, but carry 54% of all R&D expenditure.
- >10 year-old company claims are also larger: a median of $474k against $318k for companies aged 10 or under.
- The proposed rule restricts the refundable offset to a company's first 10 years (15 for therapeutics) from 1 July 2028. These figures describe today's cohort, not a forecast, but they show the 10-year cliff lands where the bulk of expenditure comes from.
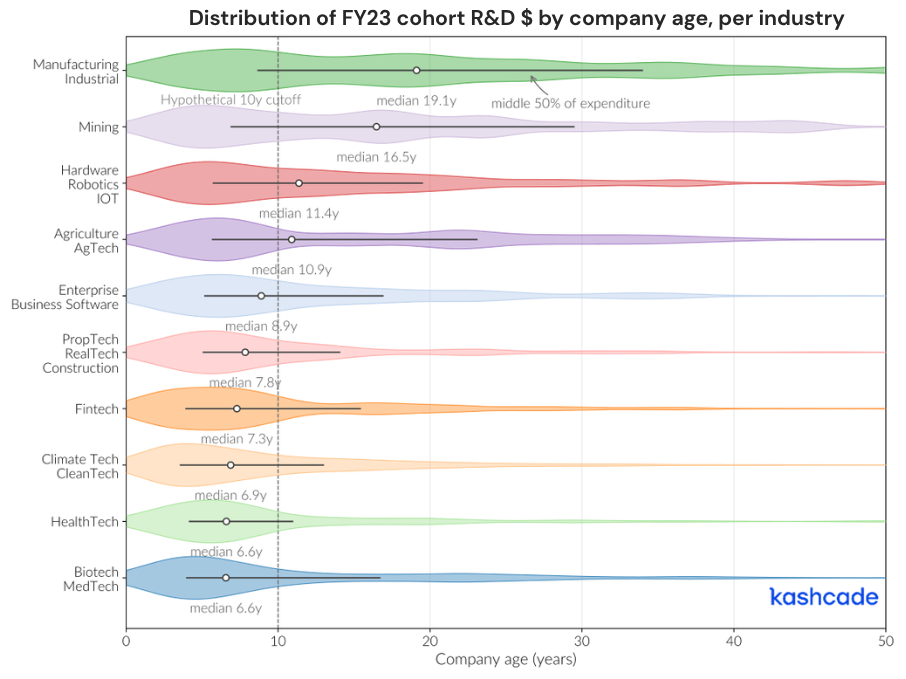
The 10-year line falls hardest on industries that build physical things
FY23 data shows many industries engage in R&D well beyond 10 years
View the data
| Industry | Median company age of R&D spend (FY23) |
|---|---|
| Manufacturing / industrial | 19.1 years |
| Mining | 16.5 years |
| Hardware / robotics / IoT | 11.4 years |
| Agriculture / agtech | 10.9 years |
| Enterprise / business software | 8.9 years |
| Proptech / construction | 7.8 years |
| Fintech | 7.3 years |
| Climate tech / cleantech | 6.9 years |
| Healthtech | 6.6 years |
| Biotech / medtech | 6.6 years |
- Manufacturing's R&D sits with companies a median 19.1 years old, and more than two thirds of its spend comes from companies past year 10. Mining (16.5 years), hardware (11.4) and agriculture (10.9) also sit past the line.
- Biotech and medtech have one of the youngest medians, at 6.6 years. Their older companies still spend heavily, with claim sizes peaking around years 15 to 17.
- The policy exposure draft extends refundability to 15 years for therapeutic-goods R&D only. The median age of manufacturing and mining R&D sits beyond even that line.
Note: Data represents the FY23 RDTI claimant population from the original FY23 ATO transparency report, matched to company age and industry. Top 100 claimants by R&D spend excluded to limit outlier distortion. Industry classifications are Kashcade’s own.
Restricting refundable offsets to the first 10 years of operation lands on the program’s centre
Companies past year 10 make up 37% of claimants and hold 54% of the program's R&D expenditure. How many currently receive the refundable offset cannot be read from the data, but the exposed group is not marginal: these are the program's largest and most established claimants, and for those under the turnover threshold the change converts an annual cash refund into a tax credit that only has value once they turn a profit.
The Budget also lifts the refundable turnover threshold to $50 million, but with refundability limited to those in their first 10 years, the wider door opens only for the very rare young, hyper-growth companies. The 15-year carve-out for therapeutics companies concedes the core problem: R&D cycles run long. Mining, manufacturing, agriculture and hardware run on the same clocks, without the exemption.
A significant portion of claimants we support for the refundable R&D tax offset are companies more than 10 years old. The Government’s proposed removal of refundability of the offset for companies more than 10 years old could have a devastating impact on a key part of our innovation and start-up ecosystem.
This was not a recommendation from the Strategic Examination of R&D (SERD) lead by a panel of innovation experts, and William Buck believes it will stifle the core of innovation in Australia.
The proposed $50k floor: who falls below it
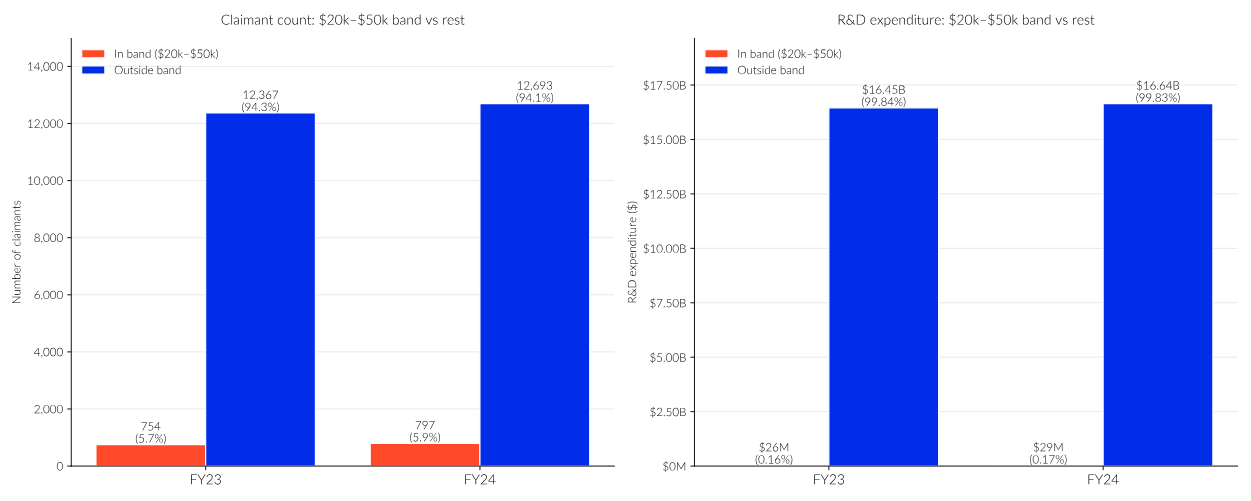
The 2026 Budget proposes lifting the minimum expenditure threshold from $20,000 to $50,000. ~7% of FY24 claimants fit that bucket, but made up only 0.17% of claimed expenditure.
View the data
| FY23 | FY24 | |
|---|---|---|
| Claimants spending $20k–$50k | 754 (5.7%) | 797 (5.9%) |
| Claimants spending more | 12,367 (94.3%) | 12,693 (94.1%) |
| Expenditure in the $20k–$50k band | $26M (0.16%) | $29M (0.17%) |
| Expenditure outside the band | $16.45B (99.84%) | $16.64B (99.83%) |
Although ~7% of R&D claimants fall below the proposed $50,000 threshold, the more important consideration is who those businesses are.
Those most likely to be affected are often early-stage companies and start-ups, which have historically been a key focus of the R&D Tax Incentive and an important driver of innovation in Australia.
The claimants
Survival, returning claimants, company age, claim size and company type.
RDTI claimants fail at a fraction of the rate of the average Australian company
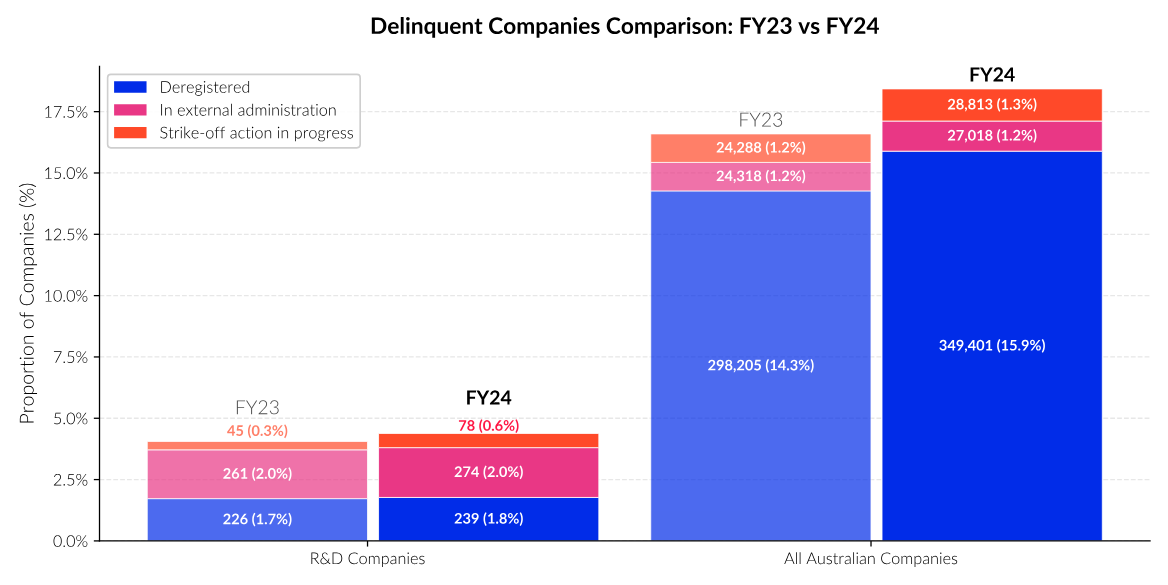
Over an approximate 3-year period (not per annum), failure rates across all Australian companies climbed to 15.9%, while less than 2% of FY24's RDTI claimants failed. That gap is roughly 9x.
View the data
| Status | RDTI claimants FY23 | RDTI claimants FY24 | All companies FY23 | All companies FY24 |
|---|---|---|---|---|
| Deregistered | 226 (1.7%) | 239 (1.8%) | 298,205 (14.3%) | 349,401 (15.9%) |
| In external administration | 261 (2.0%) | 274 (2.0%) | 24,318 (1.2%) | 27,018 (1.2%) |
| Strike-off action in progress | 45 (0.3%) | 78 (0.6%) | 24,288 (1.2%) | 28,813 (1.3%) |
RDTI failure rate since July 2023, ~9x lower than all Australian companies (15.9%).
RDTI administration in the FY24 cohort at September 2026.
Note: Company status is taken from the ABR roughly three years after each financial year began. E.g. the FY24 figures show how many companies active in FY24 had been deregistered, entered administration or faced strike-off by September 2026. All-company figures include companies registered up to 31 December after the year ended.
What the survival rates tell us
RDTI claimants failed at a fraction of the national rate, and the gap widened this year.
Failure across all Australian companies over a three-year period climbed from 14.3% to 15.9%, while the RDTI cohort held under 2%. Whatever pressure the broader economy applied, R&D claimants absorbed it better.
Two forces likely drive the gap. Companies that invest in R&D tend to be more attractive to investors and better run, so some of the difference is selection. But the R&D offset itself is cash flow arriving each year, and for R&D-stage companies the refundable offset can be the difference between extending runway and running out. Both stories can be true at once, and the data cannot fully separate them.
The R&D Tax Incentive doesn’t make a business successful. But it does give companies more runway. Sometimes that extra cash is what lets them keep the engineers, keep the project going and actually get it to market.
77% of FY23 claimants returned in FY24
Returned from FY23 (77% of FY23 claimants).
Did not return in FY24 (23% of FY23 claimants).
New entities claimed in FY24 (25% of FY24 claimants).
- 77% of companies returned to the RDTI program in FY24 after claiming in FY23.
- The 23% of companies that did not return in FY24 spent, on average, $653k on RDTI in FY23, and were ~6 years old at the time.
- New claimants in FY24 were ~4 years old and claimed an average of $554k, below the program mean of $1.24M.
Note: Returned and did not return are shares of FY23's 13,121 claimants; new entities are a share of FY24's 13,490. Company age is the median at the relevant EOFY.
Repeat RDTI claimants kept spending on R&D between FY23 and FY24
Returning claimants spent $14.8B on R&D in FY24, up 2% on the year before. However, the share of returners cutting their claim rose from 36% to 40%.
The 5% rule
- 4,932, or 49% of returning FY23 companies, upped their FY24 claim by at least 5%.
- 1,147, or 11% of companies, maintained a consistent (within +/- 5%) expenditure.
- 4,021, or 40% of companies reduced their claim by at least 5%.
The mix shifted toward reductions
- In FY23, 53% of returners upped their claim and 36% reduced. In FY24 the gap closed to 49% and 40%, respectively.
- That shift helps explain why program expenditure growth settled to 1% despite record participation. More companies claimed; fewer grew their claims.
- Companies that left the program had a median FY23 claim of $206k, roughly half the typical returning claim. Churn concentrates at the small end.
Note: The median age of the FY24 cohort was 7 years.
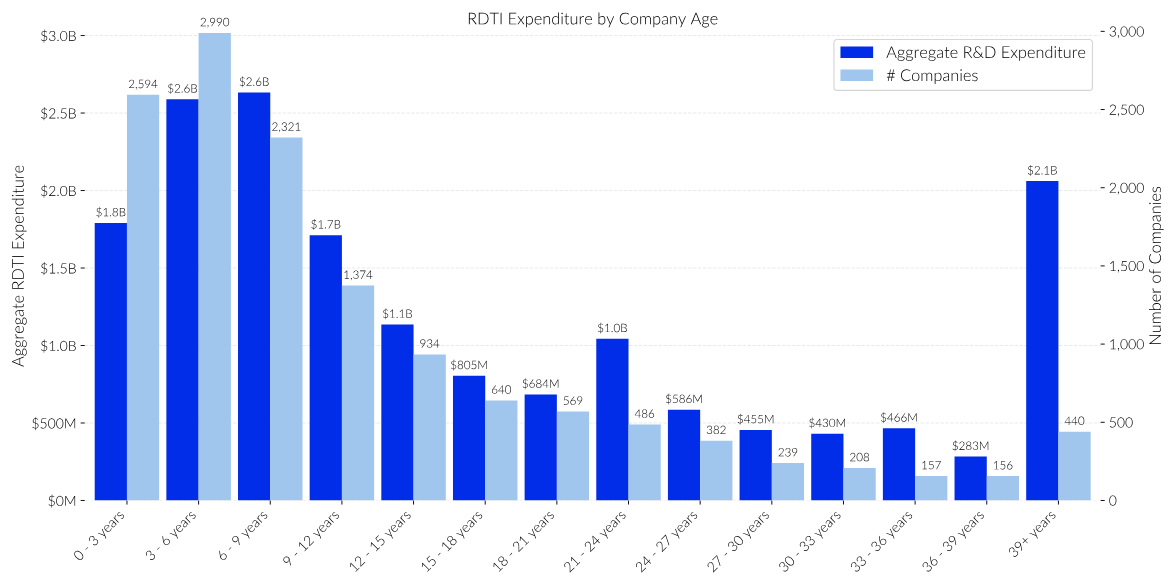
Early-stage companies are still the biggest participants in the RDTI program
Young companies still dominate RDTI participation, but the program is ageing.
View the data
| Company age | R&D expenditure | Claimants |
|---|---|---|
| 0–3 years | $1.8B | 2,594 |
| 3–6 years | $2.6B | 2,990 |
| 6–9 years | $2.6B | 2,321 |
| 9–12 years | $1.7B | 1,374 |
| 12–15 years | $1.1B | 934 |
| 15–18 years | $805M | 640 |
| 18–21 years | $684M | 569 |
| 21–24 years | $1.0B | 486 |
| 24–27 years | $586M | 382 |
| 27–30 years | $455M | 239 |
| 30–33 years | $430M | 208 |
| 33–36 years | $466M | 157 |
| 36–39 years | $283M | 156 |
| 39+ years | $2.1B | 440 |
- In FY24, the median age of an RDTI claimant rose to 7.3 years, from 7.0 years in FY23 and 6.8 in FY22.
- Companies aged 0-3 years fell 8% to 2,594, the only young band to shrink, and 3-6 years (2,990 companies) remains the largest cohort.
- The biggest lift in expenditure came from companies aged 9-12 years, up 17% to $1.7B. The R&D-scale-up phase is arriving later.
Commercialisation takes continuous R&D, and the RDTI funds it
The RDTI program was designed to mirror the innovation lifecycle, supporting companies from their early stages through to commercialisation
Brightspace builds a live digital twin of commercial buildings, and our hardware and software technology optimise the HVAC, saving costs and improving sustainability.
Every dollar we get back through the RDTI goes into the next round of R&D, and that cycle has kept our technology moving forward year after year. Even as we commercialise across APAC, getting the technology right takes continuous iteration, and the RDTI is critical in enabling this.
Average RDTI expenditure held flat in FY24
Average claim sizes barely moved between FY23 and FY24. FY24's growth came from more companies claiming rather than companies claiming more, with the distribution steady across every band.
Mean expenditure, ▾2% from $1.26M in FY23.
Median expenditure, flat on $372k in FY23.
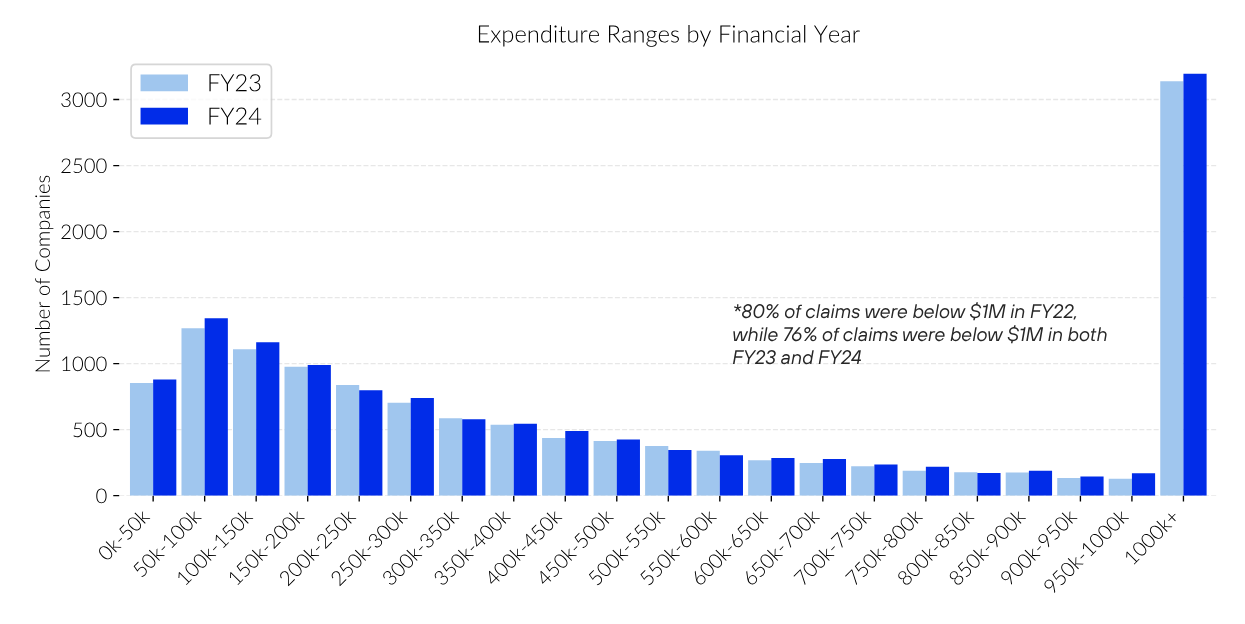
*80% of claims were below $1M in FY22, while 76% of claims were below $1M in both FY23 and FY24
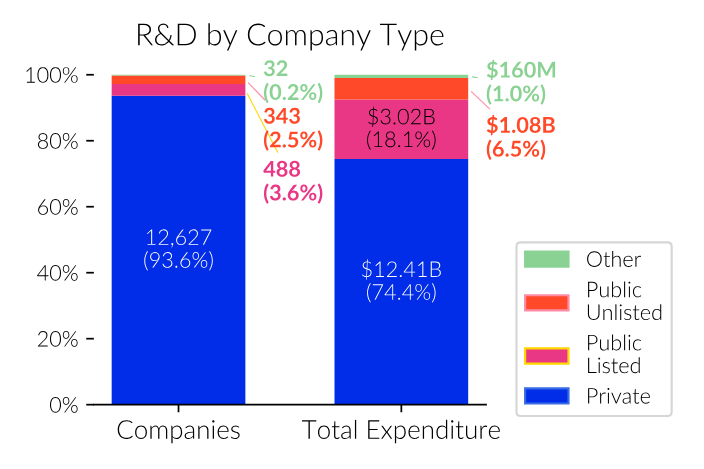
Most RDTI claimants are private companies
View the data
| Company type | Claimants FY24 | Expenditure FY24 | Average FY23 | Average FY24 |
|---|---|---|---|---|
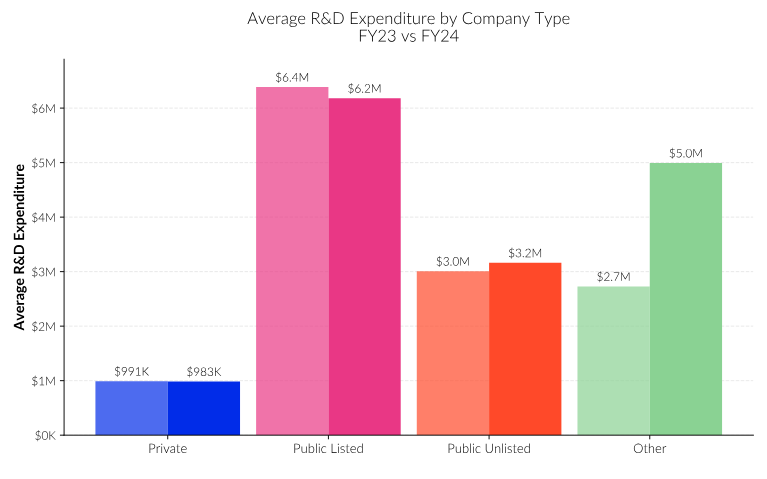
| Private | 12,627 (93.6%) | $12.41B (74.4%) | $991k | $983k |
| Public listed | 488 (3.6%) | $3.02B (18.1%) | $6.4M | $6.2M |
| Public unlisted | 343 (2.5%) | $1.08B (6.5%) | $3.0M | $3.2M |
| Other | 32 (0.2%) | $160M (1.0%) | $2.7M | $5.0M |
The program keeps shifting toward private companies: they grew to 93.6% of claimants (up 0.5 percentage points on FY23) and lifted their share of expenditure to 74.4% from 73.5%.
Average RDTI expenditure remains highest in Public Listed companies at $6.2M, roughly six times the private company average, though it eased 3% on FY23.
The top end
Atlassian, the top ten, and what they spend per Australian employee.
Atlassian tops the RDTI list for the third year running
With $236M in expenditure claimed, Atlassian is one of two claimants that would benefit from the proposed cap increase to $200M.
- Founded in Sydney in 2002, Atlassian is Nasdaq-listed and incorporated in the US, with its global headquarters in Sydney. In 2024, it reported that half its employees work in R&D.
- Atlassian Australia 1 Pty Ltd claimed $236.3M in FY24, ▴7% on $220.2M in FY23, six times greater than total program spend growth of 1.2%.
- This claim represents 1.4% of all RDTI expenditure. It equals the combined spend of about 640 median claimants and is 52% larger than the next-largest, Fortescue ($155.2M).
- Only Atlassian and Fortescue spent above the current $150M cap, so they are the only claimants that gain from lifting it to $200M. On FY24 spend, Atlassian would still sit $36M above the new cap.
Top 10 contributors in FY24
Share of all RDTI expenditure in FY24 claimed by the top 10 companies.
In FY24, the top 10 claimants represented 7.4% of all RDTI expenditure (totalling $1.23B), up from $1.16B in FY23.
Similarly, 10% of all RDTI expenditure came from only the top 18 companies, or 0.1% of all participants, unchanged from FY23.
The May 2026 Budget proposed lifting the expenditure cap from $150M to $200M from 1 July 2028. On FY24's numbers, two claimants sit above the current cap: Atlassian and Fortescue.
The FY24 data indicates the policy reform rewards few companies at the very top, while removing ~800 of claimants at the bottom through the proposed $50,000 expenditure floor. Together with the proposed disqualification of supporting activities, these two cuts could eliminate a much greater portion of program participants.
Note: FY23 comparisons use the restated complete dataset. Concentration shares are of total expenditure using amended claim amounts. Reform figures describe the FY24 cohort.
A familiar top ten, with two new names
| Rank | Company | RDTI Expenditure |
|---|---|---|
| 1 | Atlassian | $220,184,724 |
| 2 | Fortescue | $150,753,868 |
| 3 | Cochlear | $136,678,581 |
| 4 | Manildra Group (GOTW) | $117,672,586 |
| 5 | CSL | $111,543,007 |
| 6 | ResMed | $106,731,383 |
| 7 | Chevron Australia | $95,768,477 |
| 8 | Afterpay (Lanai) | $80,945,334 |
| 9 | Rio Tinto | $73,157,842 |
| 10 | Molycop (Grinding Media) | $68,814,589 |
| Rank | Change | Company | RDTI Expenditure |
|---|---|---|---|
| 1 | = | Atlassian | $236,287,319 ▴7.3% |
| 2 | = | Fortescue | $155,183,626 ▴2.9% |
| 3 | = | Cochlear | $145,768,412 ▴6.7% |
| 4 | ▴1 | CSL | $111,193,525 ▾0.3% |
| 5 | ▴4 | Rio Tinto | $105,199,647 ▴43.8% |
| 6 | = | ResMed | $104,015,053 ▾2.5% |
| 7 | ▴1 | Afterpay (Lanai) | $101,901,863 ▴25.9% |
| 8 | ▾1 | Chevron Australia | $98,185,698 ▴2.5% |
| 9 | ▴2 | Shell Energy | $85,910,938 ▴25.3% |
| 10 | ▴1083 | Kilcoy Global Foods (Blacqua) | $85,288,568 ▴2950.9% |
Manildra Group (GOTW) and Molycop (Grinding Media) left the top ten, falling 271 and 29 places. Shell Energy (up 2) and Kilcoy Global Foods (Blacqua, up 1,083) entered it.
The top ten claimants employ ~57k people in Australia*
Median R&D spend per Australian employee among the top ten claimants.
Top ten claimants: Australian employees and R&D spend per employee
| Rank | Company | AU employees* | R&D spend per AU employee |
|---|---|---|---|
| 1 | Atlassian | 3,500 | $67,511 |
| 2 | Fortescue | 12,000 | $12,932 |
| 3 | Cochlear | 2,300 | $63,378 |
| 4 | CSL | 3,100 | $35,869 |
| 5 | Rio Tinto | 26,000 | $4,046 |
| 6 | ResMed | 1,600 | $65,009 |
| 7 | Afterpay (Lanai) | 1,000 | $101,902 |
| 8 | Chevron Australia | 1,900 | $51,677 |
| 9 | Shell Energy | 2,800 | $30,682 |
| 10 | Kilcoy Global Foods (Blacqua) | 2,600 | $32,803 |
*Australian employees: corporate-group headcount reported to WGEA for 2023-24 (1 Apr 2023 – 31 Mar 2024), rounded to the nearest hundred
The map
Where R&D spend sits, by state and by area.
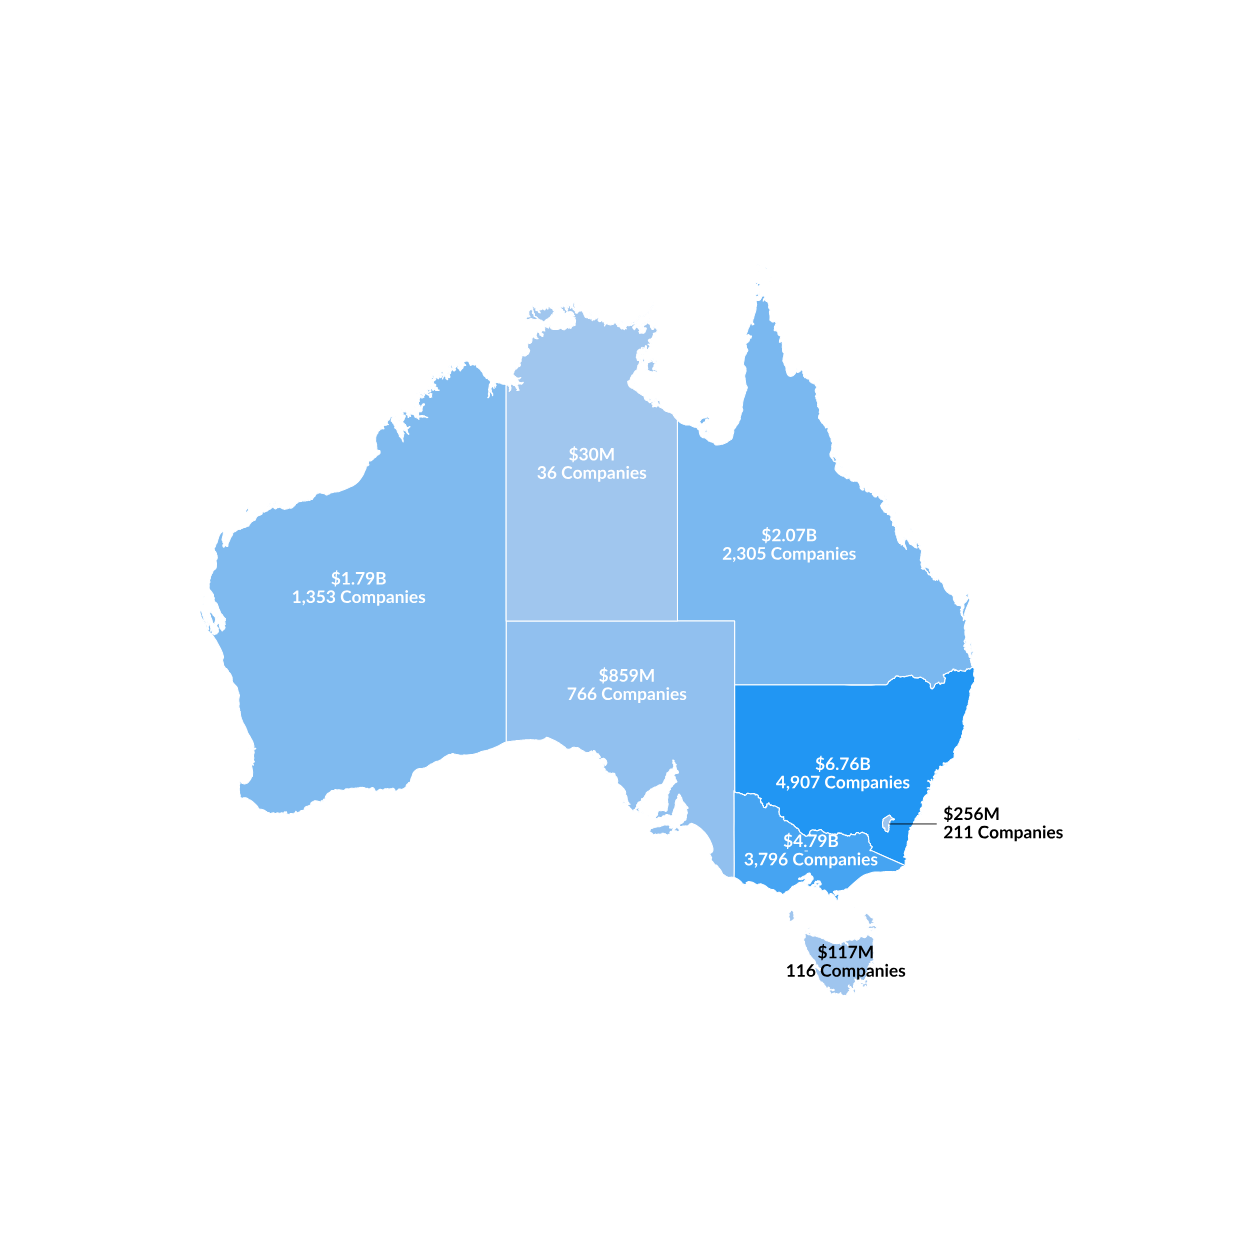
NSW and VIC still anchor the nation's R&D
View the data
| State | R&D expenditure FY24 | Claimants FY24 |
|---|---|---|
| NSW | $6.76B | 4,907 |
| VIC | $4.79B | 3,796 |
| QLD | $2.07B | 2,305 |
| WA | $1.79B | 1,353 |
| SA | $859M | 766 |
| ACT | $256M | 211 |
| TAS | $117M | 116 |
| NT | $30M | 36 |
- NSW (36%) and VIC (28%) remain home to most claimants and 69% of all R&D expenditure. Combined spend across the two was flat, with NSW up slightly and VIC easing.
- The largest dollar rise was in SA, up 20% to $859M with claimant numbers up 9%, leaving it just short of joining NSW, VIC, QLD and WA above the $1B mark.
- Median expenditure per claimant fell in NSW, VIC, WA and the ACT, consistent with the flat typical claim across the program.
Note: State is assigned per companies’ main business location listed on the ABR; excludes claimants whose ABN does not map to a state. Medians per claimant by state. FY23 comparisons use the restated complete dataset.
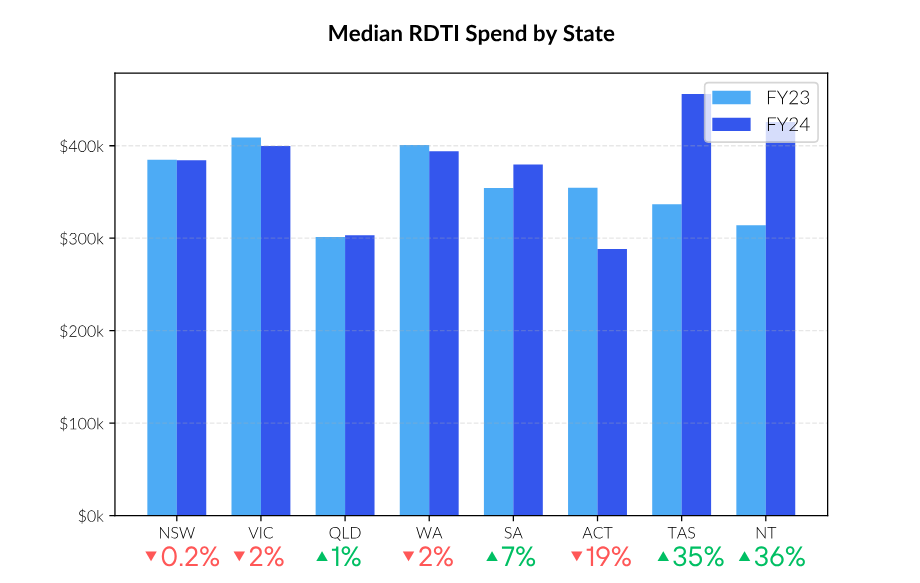
Median R&D expenditure was steady to slightly lower across the major states
View the data
| State | Median spend FY24 | Change on FY23 |
|---|---|---|
| VIC | $400k | ▾2% |
| WA | $394k | ▾2% |
| NSW | $384k | ▾0.2% |
| SA | $380k | ▴7% |
| QLD | — | ▴1% |
| ACT | — | ▾19% |
| TAS | — | ▴35% |
| NT | — | ▴36% |
- VIC ($400k), WA ($394k) and NSW ($384k) again posted the highest medians among them, each easing marginally on FY23.
- SA was the standout of the larger states, with its median up 7% to $380k on 9% more claimants, the only mainland state to record meaningful median growth.
- TAS (▴35%) and NT (▴36%) posted the largest rises, but on 116 and 36 claimants these medians move on a handful of claims.
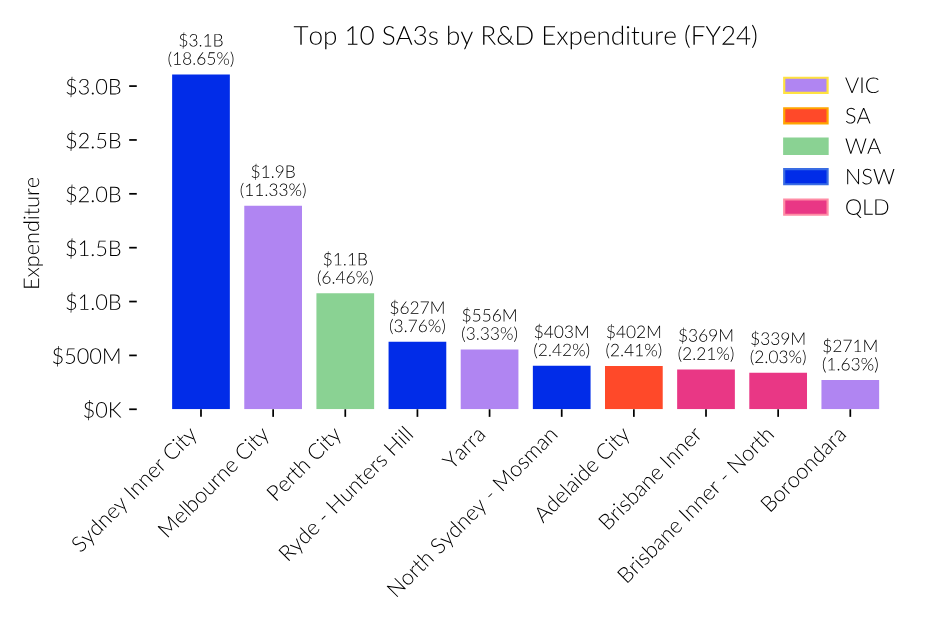
RDTI expenditure remained concentrated in city CBDs in FY24
RDTI activity remained centralised to city centres:
- The majority (54%) of RDTI expenditure came from companies registered in the top 10 areas, easing from 56% in FY23.
- The top 3 areas, Sydney Inner City, Melbourne City and Perth City, accounted for 36% of expenditure and 21% of participants.
- Sydney Inner City alone held $3.1B across 1,455 companies, 19% of all program expenditure from a single area, though its total eased 3% on FY23.
- The distribution is thin-tailed beyond the capitals: outside the top 10 areas, no single SA3 reached $270M.
View the data
| Area (SA3) | State | R&D expenditure FY24 | Share |
|---|---|---|---|
| Sydney Inner City | NSW | $3.1B | 18.65% |
| Melbourne City | VIC | $1.9B | 11.33% |
| Perth City | WA | $1.1B | 6.46% |
| Ryde – Hunters Hill | NSW | $627M | 3.76% |
| Yarra | VIC | $556M | 3.33% |
| North Sydney – Mosman | NSW | $403M | 2.42% |
| Adelaide City | SA | $402M | 2.41% |
| Brisbane Inner | QLD | $369M | 2.21% |
| Brisbane Inner – North | QLD | $339M | 2.03% |
| Boroondara | VIC | $271M | 1.63% |
Participation
How many companies claim, what the program costs, and how Australia compares.
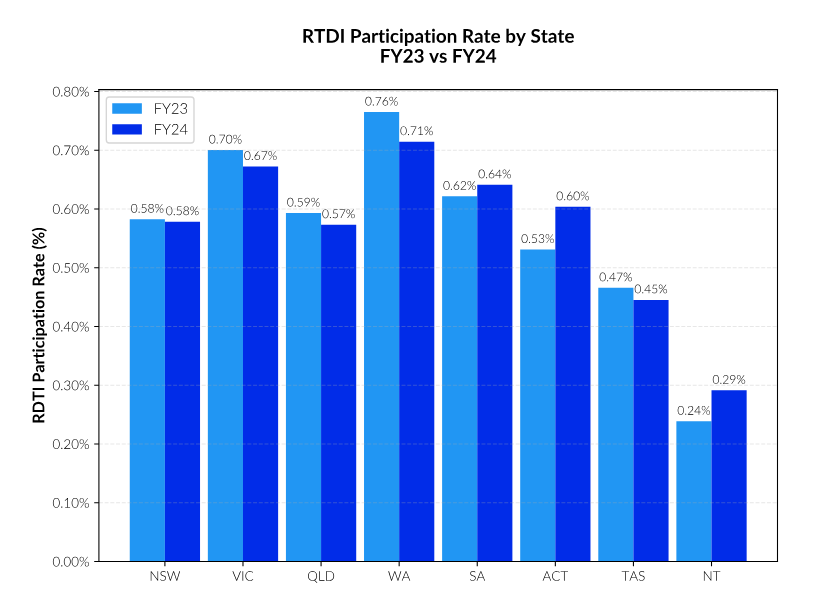
FY24 company participation remained low, and slipped on FY23
FY24 participation rate, down from 0.63% in FY23 (▾2% year on year).
View the data
| State | FY23 | FY24 |
|---|---|---|
| NSW | 0.58% | 0.58% |
| VIC | 0.70% | 0.67% |
| QLD | 0.59% | 0.57% |
| WA | 0.76% | 0.71% |
| SA | 0.62% | 0.64% |
| ACT | 0.53% | 0.60% |
| TAS | 0.47% | 0.45% |
| NT | 0.24% | 0.29% |
| Australia | 0.63% | 0.61% |
- Only 1 out of every 163 companies in Australia participated in the RDTI program in FY24 (down from 1 in 159).
- This is the first decline in the report's coverage: company registrations grew 5% while claimant numbers grew 3%.
Note: Participation is claimants over all registered Australian companies, by state of main business location listed on the ABR. FY23 restated to the complete dataset (previously published as 0.62%, 1 in 161).
Businesses with <$20M turnover continue to grow the program
The refundable component of the program continues to grow while non-refundable stagnates.
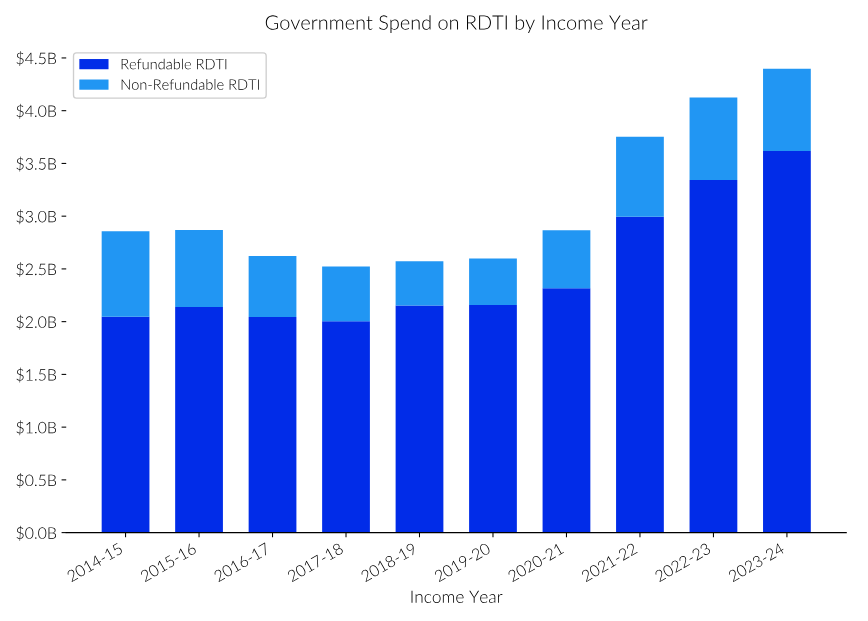
- All growth in the program's cost came from refundable offsets, up 8% to $3.6B, while non-refundable held flat at $780M for a second year.
- The RDTI cost the budget $4.4B in FY24, around 0.16% of GDP and roughly a third of all government investment in R&D. For that outlay, claimants reported $16.7B of R&D expenditure, nearly four dollars of business R&D for every public dollar of program cost.
Source: DISR Science, Research and Innovation budget tables, cost to the budget by income year. A separate source from the ATO transparency data; figures for recent years may be estimates subject to revision. Refundable offset eligibility: aggregated turnover under $20 million.
Australia still trails on R&D support, and the UK shows how fast a program can shrink
The RDTI made up 32% of all government investment in R&D in FY24 ($4.4B of $13.9B). Total government R&D spend was 0.52% of GDP, well below the 2022 OECD average of 0.73%.
But participation remained low and slipped: 0.61% of Australian companies claimed in FY24, versus roughly 1.6% in Canada, where participation is still rising.
UK participation roughly halved in two years to about 0.85% after reforms cut rates and added mandatory reporting. Claims fell 26% in 2023-24 alone, with small-company claims down 31% and first-time claimants down 45%. The parallel for Australia is direct. The UK's added friction led to its smallest claimants exiting first.
Canada: SR&ED program statistics, 2023-24 program year, 21,537 claimants. 1.36M companies per Statistics Canada.
UK: HMRC R&D tax relief statistics, September 2025 release, 2023-24 tax year (46,950 claims, ~5.5M registered companies); first published estimates, subject to revision.
Participation rates are indicative; company-base definitions differ across countries.
As an R&D consultant in the UK, I saw firsthand how smaller and early-stage companies found the program harder to engage with as it tightened, and many stopped claiming.
Australia's proposed reforms show parallels, and there are lessons in that worth considering.
Closing thoughts
The FY24 data shows signs of consolidation. Participation already trails comparable countries, and slipped in FY24, and 40% of returning claimants reduced their spend.
The proposed policy changes would shape the program for years. Through the consultation period, four questions need to be considered:
- Where does the next generation of claimants start? Small claims are how companies enter the program. The proposed floor sits above 792 of them. With the removal of supporting activities, this figure may be in the thousands.
- What funds R&D in a company's second decade? The average R&D cycle continues for years, but the refund would stop at year 10.
- If one industry needs 15 years, which others do? Manufacturing, deep-tech, agriculture, hardware, and many more industries run on clocks as long as therapeutics. Choosing industries is not how the program was designed.
- What happens to grassroots innovation? General participation slipped to 1 in 163 companies in FY24. When the UK tightened its scheme, first-time claimants fell 45% in a single year.
Our follow-up editions will continue to test these questions against the data. We encourage the R&D community to keep the discussion going as the policy unfolds.
Interested in receiving your RDTI rebate early?
An R&D loan from Kashcade can help extend your runway and enable you to invest in more R&D. To find out more, visit kashcade.com
Get funded today >Interested in more detail?
Kashcade will release a more in-depth analysis following this initial version. Register your interest by reaching out to us at RDTIReview@kashcade.com and be notified when it releases.
RDTIReview@kashcade.comRDTI FY24: frequently asked questions
What is the R&D Tax Incentive (RDTI)?
The Research and Development Tax Incentive (RDTI) is the Australian Government's main program for supporting business R&D. Eligible companies receive a tax offset on their R&D expenditure. Companies with aggregated turnover under $20 million can receive a refundable offset, paid as cash even when they make a loss, while larger companies receive a non-refundable offset that reduces tax payable. The program is jointly administered by the ATO and the Department of Industry, Science and Resources.
How much R&D expenditure was claimed under the RDTI in FY24?
13,490 companies claimed a record $16.7 billion of R&D expenditure under the RDTI in FY24 (the 2023-24 income year). Claimants grew 3% and expenditure 1% like for like on FY23, restated to 13,121 claimants and $16.5 billion.
Which companies claimed the most under the RDTI in FY24?
Atlassian topped the list for the third year running with $236.3 million of R&D expenditure, followed by Fortescue ($155.2 million) and Cochlear ($145.8 million). The top 10 claimants accounted for $1.23 billion, or 7.4% of all RDTI expenditure.
What changes to the RDTI are proposed in the 2026-27 Budget?
Treasury's exposure draft would raise offsets for eligible core R&D, lift the refundable offset turnover threshold from $20 million to $50 million, lift the maximum expenditure threshold from $150 million to $200 million, and lower the non-refundable intensity threshold from 2% to 1.5%. It would also remove supporting R&D activities from eligibility, raise the minimum expenditure threshold from $20,000 to $50,000, and limit the refundable offset to companies up to 10 years old, or 15 years for eligible therapeutic-goods R&D, from 1 July 2028.
How many RDTI claimants are more than 10 years old?
In FY24, 5,009 claimants (37%) were more than 10 years old, and they carried 54% of all R&D expenditure ($9.0 billion). The data does not show how many currently receive the refundable offset. In Kashcade's FY23 industry analysis, the median company age of R&D spend was 19.1 years in manufacturing and 16.5 years in mining.
How many companies fall below the proposed $50,000 RDTI minimum?
About 7% of FY24 claimants sit below the proposed $50,000 floor. Together they made up only 0.17% of claimed expenditure.
How much does the RDTI cost the government?
The RDTI cost the budget $4.4 billion in FY24, around 0.16% of GDP: $3.6 billion in refundable offsets (up 8%) and $780 million in non-refundable offsets. Claimants reported $16.7 billion of R&D, nearly four dollars of business R&D for every public dollar of program cost.
How does Australia's R&D tax incentive participation compare with other countries?
0.61% of Australian companies claimed the RDTI in FY24, about 1 in every 163, down from 0.63% in FY23. That compares with roughly 1.6% in Canada and about 0.85% in the UK, where participation roughly halved in two years after reforms.
Are RDTI claimants less likely to fail?
Yes. 1.8% of FY24 RDTI claimants had been deregistered by September 2026, compared with 15.9% of all Australian companies over a similar three-year period, roughly 9x lower.
About the data
This analysis uses the ATO's R&D Tax Incentive transparency report for the 2023-24 income year, which lists each claimant's R&D expenditure. Kashcade matched claimants to ABR records for company age, state, area and status, and to WGEA headcounts. Program cost comes from DISR's Science, Research and Innovation budget tables, and international comparisons from CRA SR&ED and HMRC statistics. FY23 figures are restated to the complete dataset. Industry classifications are Kashcade's own.
- ATO: R&D tax incentive transparency reports
- DISR: Science, Research and Innovation budget tables
- HMRC: Research and development tax credits statistics
- Treasury: open consultations

